MCA Loans and the Debt Ladder: A CFO’s Guide
TL;DR
- A merchant cash advance (MCA) is the fastest, easiest and most expensive way to raise working capital. A 30% factor repaid in weekly debits over 90 days works out to an APR of roughly 207%.¹
- It is defensible only for a short, specific emergency with a known repayment source, such as a construction company bridging a buyer deposit.
- Payment-first collection, personal guarantees and stacking can turn a bridge into a trap.
- The debt ladder runs from bank lines (7% to 12%) to ABL (15% to 25%) to factoring (30% to 50%) to MCAs (50% and up). Sit on the lowest rung you qualify for, with a plan to climb.
- For concentrated, high-growth customers, factoring or ABL can beat a bank line: their ceilings flex, and the liquidity is worth a few points of interest.
The 48-Hour Yes That Can Cost You the Business
A merchant cash advance (MCA) is the fastest money a small business can get. Approval often comes in 24 to 48 hours, on a few months of bank statements, with little regard for credit score or last year’s losses. For an owner staring at a payroll gap, that speed feels like rescue.
The price of the speed is steep. On a typical 1.30 factor, the APR runs from roughly 54% if repaid over a year to over 200% if repaid in 90 days, and the structure of the product can turn one emergency into a permanent cycle. Fractional CFOs see this patter in founder-led and family-owned businesses, so it is worth laying out plainly. Usually, it occurs when there is a dislocation of something in the business or a lack of predictability in cash flow where gut instincts fail to provide the right view on the future of cash. We’ve seen things like losing a major customer, getting into a dispute on receivables or hiring too many sales people as causes of issues, but the reasons can be a wide range.
This article does two things. First, it explains how MCAs actually work, what they really cost, and when they are defensible. Second, it introduces the debt ladder: a way of thinking about capital as a progression from the most expensive, most accessible financing at the bottom to the cheapest, most selective at the top. An MCA belongs on the bottom rung. It’s important to note that MCAs always lead with “non-dilutive” financing, meaning they don’t take ownership in your business, but make not mistake, the rates charged on these loans are equity rates at a minimum. So, economically, it’s as costly as selling an ownership stake in your business, with the added stress of having to pay this owner on a weekly basis.
The CFO’s job is to make sure you can avoid it.
What an MCA Actually Is
An MCA is not a loan. Legally, it is the purchase of a slice of your future receivables, meaning your revenues. The provider advances a lump sum and, in return, buys the right to a set amount of your future credit card sales or bank deposits. A typical deal advances $100,000 in exchange for $130,000 of future receivables. That 1.30 is the factor rate.
Because it is structured as a purchase, MCA providers largely sit outside lending rules. Usury caps, truth-in-lending disclosures and licensing generally do not apply, which is how rates that would be illegal on a loan are permitted here. It also explains the vocabulary: “factor rate” sounds friendlier than “30% fee,” and few owners convert it to an annual percentage before signing.
Let’s look at an example. Let’s say a construction company is waiting on a buyer deposit to start construction, but they incurred costs before the deposit because the construction permit duration required them to start the project. The construction company is short $1 million to vendors and contractors so they obtain an MCA loan knowing the buyer deposit will come in 90 days. Let’s say the factor is 30% on a 90-day advance. Through the 90 days, the construction company will pay $1.3 million back to the MCA company and that equates to an APR of roughly 207%.¹
Repayment is automatic, and it comes out of your bank account whether or not the deposit has arrived. A construction company waiting on a buyer deposit has no sales to withhold from, so the provider debits the account directly. In our example, $1.3 million over about 13 weeks works out to $100,000 every week. There is no payment calendar to manage and nothing to miss. That certainty is why a provider will fund a company with a strained balance sheet: the collection mechanism is the security, not the credit file.
Businesses with steady card sales see the same mechanics a different way. A restaurant or retailer typically repays through a fixed percentage of daily receipts, taken by the card processor before the money reaches the account. At 20% withholding, a $10,000 sales day sends $2,000 to the provider, and a $2,000 day sends $400. Either way, the provider is paid on its schedule, not yours.
Two features matter more than the headline rate. First, the MCA is paid first, ahead of rent, payroll and suppliers. For our construction company, the $100,000 weekly debit comes out before the subcontractors the advance was meant to cover. Second, personal guarantees typically accompany the deal. If the project stalls after the company has repaid $800,000 of the $1.3 million, the owner can still owe the $500,000 balance.
The True Cost: Converting Factor Rates to APR
A factor rate hides time. The same 30% fee can be tolerable or ruinous depending on how fast you repay.
Back to the construction company. It borrows $1 million and owes $1.3 million, so the cost is $300,000. A quick shortcut, 30% over 90 days scaled to a year, gives about 120%, but it understates the cost because the weekly debits return the lender’s money long before day 90. The APR method accounts for this. With 13 weekly debits of $100,000, the APR is about 207%.¹ The same $300,000 over different timelines looks like this:
| Time to repay the $1.3 million | APR on the $1 million advance¹ |
| 52 weeks, $25,000 a week | ~54% |
| 26 weeks (~180 days), $50,000 a week | ~107% |
| 13 weeks (~90 days), $100,000 a week | ~207% |
| 9 weeks (~60 days), $144,444 a week | ~291% |
Speed drives the result, and the shorter the repayment, the higher the APR, because each weekly debit shrinks the balance you still owe and the $300,000 is charged against less and less borrowed money. For comparison, a traditional bank line runs roughly 7% to 12%.
Ask every provider for three things in writing: the total payback amount, the expected repayment period, and the implied annual rate. A reputable provider will answer. Reputable factor rates generally fall between 1.15 and 1.40. Predatory ones approach 2.0, meaning you repay double.
Rate is not the only cost; cash flow is the other. The construction company has no revenue until the deposit arrives, so the $100,000 weekly debit has to come from somewhere. If the deposit slips even a month, the debits alone leave a $400,000 hole. That is how an MCA taken to solve a cash problem creates the next one.
When an MCA Makes Sense, and When It Is a Trap
An MCA is defensible in one narrow situation: a genuine short-term emergency where capital must arrive in 24 to 48 hours, the repayment source is known, and no cheaper option exists.
Our construction company is a defensible case, with conditions. The permit forced an early start, so costs landed before the deposit. The repayment source is known: a buyer deposit due in 90 days. Stopping work would put the permit and the project at risk. The test is whether the deposit is contractual, the buyer is creditworthy, and the project’s profit clearly exceeds the $300,000 cost. If any of those answers is shaky, the MCA is a gamble, not a bridge. For example, let’s say the buyer’s contract commits to a $350,000 bonus to the construction company for an on-time completion; that would be a motivating factor to get the MCA.
The trap begins when the MCA stops being a bridge. Warning signs:
- Using MCAs more than once or twice a year
- Holding multiple MCAs at the same time
- Taking a new MCA to pay off the last one
- Using advances to cover ordinary operating expenses
- Staying on MCA financing beyond three to six months
Stacking is the most dangerous pattern. Suppose the buyer deposit slips 30 days. The $100,000 weekly debits keep coming, leaving a $400,000 hole. A second MCA fills it at the same 30% factor, adding $520,000 of payback and another weekly debit. The company has now taken $1.4 million in advances and owes $1.82 million, and the next gap is bigger than the first. A third MCA follows. Each one collects ahead of payroll and subcontractors, which can slow the very work that triggers the deposit.
The margin math fails too. If the project would earn $250,000 before financing costs, a $300,000 MCA fee turns it into a loss. An MCA treats a symptom. If the real problem is thin margins or bloated overhead, it accelerates the failure instead of preventing it. In our example, the bonus payment, if truly additional profit, might be a reason to do the loan.
Spotting Predatory Providers
The MCA market has professionals and predators. Five tests separate them:
- Factor rate. Reputable providers sit between 1.15 and 1.40. Rates near 2.0 mean you repay double.
- Contract clarity. Good contracts explain the rate, withholding percentage, fees and obligations in plain language. Watch for automatic renewals, undisclosed fees, and clauses that let payments rise without notice.
- Fee transparency. Ask for total cost and the implied annual rate in writing. Evasion is your answer.
- Behavior under stress. Reputable providers work with a business that hits a rough patch. Predatory ones accelerate the full balance, call daily, contact your customers or vendors, or sue at the first missed payment.
- Exit terms. Good providers reduce the cost when you pay early. If the deposit arrives on day 60, the construction company should not still owe the full $300,000. Bad ones charge the full factor rate regardless of speed and bar you from seeking other financing.
Also check reputation: years in business, a transparent legal name, client references, Better Business Bureau record, and complaint history. Have an attorney or your CFO review any MCA contract before you sign. The time it takes is cheap against a $1.3 million obligation.
The Debt Ladder: Climbing Toward Cheaper Capital
The debt ladder ties these financing types together. Cost and accessibility move in opposite directions: the easiest money to get is the most expensive, and the cheapest money is the hardest to qualify for. A business should sit on the lowest-cost rung it genuinely qualifies for, and have a plan to move up.
| Rung (top to bottom) | Effective annual cost | What the lender looks at | Best fit |
| Traditional bank line or term loan | 7% to 12% | Credit, profitability, operating history, clean financials | Stable, profitable businesses |
| Asset-based lending (ABL) | 15% to 25% | Collateral: receivables, inventory, equipment | Growth, turnaround, seasonal and acquisition situations |
| Invoice factoring | 30% to 50% | Your customers’ creditworthiness | Startups and fast growers with strong customers and thin credit |
| Merchant cash advance | 50% to 300%+ | Revenue volume | Genuine emergencies only |
ABL is a revolving line secured by collateral. Lenders advance roughly 75% to 90% against eligible receivables and 50% to 70% against eligible inventory, so a $2 million balance sheet of receivables may support only $1.2 to $1.4 million of borrowing. The trade-off is administration: borrowing base certificates, field exams, covenants. Even with a 16% all-in cost once interest, origination, monitoring and exam fees are counted, it is a fraction of an MCA.
Factoring is the sale of invoices, usually at an 80% to 90% advance. A 3% discount on a 30-day invoice looks modest but annualizes to about 42%. Customers are notified and pay the factor directly, which some find a relationship risk. Non-recourse factoring moves credit risk to the factor for a 1 to 2 point premium.
These rungs are meant to be temporary. ABL typically serves a business for two to four years. The point is to use each as a bridge toward the next rung up.
Now put the construction company on the ladder. Before accepting an MCA at a 207% APR, work down from the top. Carrying $1 million for 90 days costs roughly $17,000 to $30,000 on a bank line, $37,000 to $62,000 on ABL, and $74,000 to $123,000 through factoring, against $300,000 on the MCA. Each cheaper rung has a qualification test: a bank wants clean financials and history, ABL needs collateral such as receivables from other projects or equipment, and factoring needs creditworthy customers with open invoices. If the company qualifies for any of them, the MCA is the wrong tool. If it qualifies for none, that shows which rung it is really on.
Concentration Limits: Why a Higher Rate Can Be the Better Facility
The ladder ranks rungs by rate, but rate is not the only constraint. The size of the facility, and who sets its ceiling, often matters more once a business starts growing.
Start with concentration limits. ABL lenders cap their exposure to any single customer, commonly at 15% to 20% of eligible receivables. Anything above the cap is ineligible, however creditworthy the customer. Suppose our construction company has $5 million of receivables and one buyer owes $3 million of it, or 60%. With an illustrative 20% cap, only about $1 million of that buyer’s balance counts. At an 80% advance rate, ABL availability drops from roughly $4 million to about $2.4 million. The company’s best receivable, from its fastest-growing customer, is the one the lender discounts most.
Factoring looks at the same customer differently. A factor underwrites your customer’s credit, not your balance sheet, so a large, creditworthy buyer is an asset rather than a concentration problem. Factors still set per-customer credit limits, so confirm them up front, but those limits track the customer’s strength and can rise as the relationship grows. The rate is higher, 30% to 50% against 15% to 25% for ABL, but a lower rate on money you cannot borrow is worth nothing. Liquidity is often very valuable to a company, worth a few percentage points of interest or more. Available cash lets the business accept the next large order, pay payroll and suppliers on time, and stay off the emergency financing at the bottom of the ladder. For a business whose growth is concentrated in a few strong customers, factoring can be the better long-term facility.
Now the ceiling. A bank line is sized to your balance sheet, history and covenants, and it is reviewed on the bank’s schedule. If the bank approves $500,000 when a fast-growing business needs $1.5 million, that ceiling may not move for a year, or at all. Credit committees do not flex because your customer won a big contract.
ABL lenders and factors are paid for volume, so they want to lend more. An ABL borrowing base grows automatically as receivables and inventory grow. A factor’s capacity grows with every approved invoice. Their ceilings follow your growth instead of capping it.
The practical test is three questions: How much can the facility actually advance against my customer mix? Who controls the ceiling, and how fast can it change? What does the dollar cost look like on the amount I need, not just the percentage? Factoring’s costs are real, and customers are notified, so weigh both. But for concentrated, high-growth customers, the facility that scales is often worth more than the cheaper one that does not.
How to Climb: A CFO’s Playbook
Climbing the ladder is deliberate work. This is the sequence I would run with a client carrying MCA debt:
- Stabilize cash first. Build a rolling cash forecast so the next gap shows up weeks ahead. A 13-week view would have shown the construction company that the permit start date and the deposit date did not line up, before it needed a $1 million stopgap.
- Inventory the damage. List every advance: balance, debit schedule, remaining payback, and personal guarantees. For the construction company, that is $1.3 million owed at $100,000 a week, backed by the owner’s signature.
- Fix the underlying problem. Find why the MCA was needed: margin, overhead, collections or timing. For the construction company it is timing, so the next contract should build in deposit milestones or an earlier deposit date. Refinancing a broken model just resets the clock.
- Clean up the financials. Timely closes and credible statements are what move lenders to say yes. Better numbers are the ticket to the next rung.
- Match the next rung to the business. Valuable collateral points to ABL. Strong customers with thin credit points to factoring. Compare options by APR, never by factor rate or discount rate.
- Set graduation milestones. Typical triggers for moving up: 12 to 18 months of consistent profitability, built-up equity, and a banker who understands the business.
- Build the bank relationship early. Open treasury accounts and take a small conventional loan while you are still on ABL, so refinancing is a conversation with a known lender, not a cold call.
The payoff is real. Moving from a 16% ABL to a 9% bank line on $1.5 million of average borrowing saves about $105,000 a year, every year. But note, if you need more liquidity and flexibility don’t just look at the interest rate difference, as discussed above.
The Bottom Line
MCAs are not evil, and they are not a strategy. Our construction company used one to turn a 90-day timing gap into a $300,000 expense, roughly a 207% APR. That can be defensible once, with a contractual deposit and project profit well above the cost. Used repeatedly, stacked, or to cover ordinary operations, an MCA is the quickest route to failure a founder can sign up for.
Three takeaways:
- Convert every factor rate to an APR, using the actual payment schedule, before you sign anything.
- Treat any MCA as a bridge with a named exit, not a facility.
- Know your rung on the debt ladder and what it takes to reach the next one.
If you are carrying one or more MCAs, or you are weighing one right now, get a second set of eyes on the contract and the cash forecast before you commit. That conversation is what fractional CFOs are for. You can reach CFO Pro+Analytics at cfoproanalytics.com.
Frequently Asked Questions
What does an MCA really cost?
More than the factor rate suggests, because the rate hides time. A $1 million advance at a 1.30 factor costs $300,000. Repaid in 13 weekly debits over 90 days, that is an APR of about 207%; repaid over 26 weeks, about 107%; repaid over a year, about 54%. APR is the right yardstick because it accounts for how each debit shrinks the balance you still owe. Always ask the provider for the total payback, the repayment period and the implied annual rate in writing.
When does an MCA make sense?
Only for a short-term emergency with a known repayment source, no cheaper option, and project or business profit that clearly exceeds the cost. Our construction company fits if its buyer deposit is contractual and the buyer is creditworthy. An MCA used repeatedly, stacked, or to cover ordinary operating expenses is a warning sign, not a strategy.
Why would I choose factoring over ABL or a bank line when it costs more?
Because the cheaper facility may not lend you enough. ABL lenders cap exposure to any one customer, which penalizes concentrated, fast-growing customers. A bank line has a ceiling set by your balance sheet that may not change for a year. Factors and ABL lenders earn on volume, so their capacity grows with your receivables. Liquidity is often worth a few percentage points of interest or more.
Disclaimer: This article is for general educational purposes only and is not financial, legal, tax or investment advice. The examples, rates and figures are illustrative, and actual terms vary by provider, industry and market conditions. Every business has its own facts, including its cash flow, customers, collateral, contracts and risk tolerance, and these change the right answer. Before entering any financing arrangement, consult a qualified financial advisor, attorney or CFO who understands your situation. No professional relationship is created by reading this article.
How the APR in this article is calculated
The APR is the actuarial (internal rate of return) rate, the same approach used to quote APR on ordinary loans: the periodic rate at which the present value of all repayments equals the cash actually advanced. In the construction example, $1,000,000 is advanced and $1,300,000 is repaid in 13 equal weekly debits of $100,000:
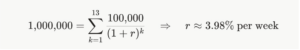
APR = 3.98% × 52 weeks ≈ 207%. The shortcut of 30% × 365 ÷ 90 gives about 122% because it assumes you hold the full $1 million until day 90, when weekly debits are in fact returning money to the lender along the way.
Assumptions and limits: equal weekly debits, no origination or other fees deducted from the advance, and payment exactly on schedule. Daily business-day debits (65 payments) raise the result to about 217%, and fees deducted at funding raise it further. If repayment is a percentage of sales, payments vary, so the APR depends on the assumed schedule. APR is quoted the conventional way, as the periodic rate times periods per year; compounding the weekly rate would give a far higher effective annual rate (about 660% in the 13-week case), so compare quotes on the same basis. Some states, including New York, require providers of sales-based financing to disclose an estimated APR using prescribed methods that may differ from this one, so read the provider’s written disclosure alongside your own calculation. The ranges shown for bank lines, ABL and factoring are typical ranges and were not recomputed this way.
